
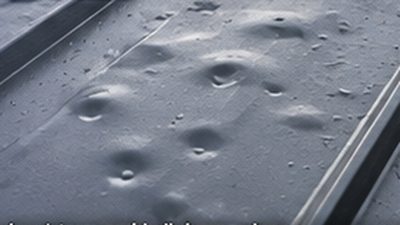
After a storm, two things happen
The first is that some roofs get damaged. The second is that the I-94 corridor fills with out-of-state crews knocking doors, and the ratio of the second to the first is not flattering.
Storms roll along this corridor every summer. Genuine hail damage is real and worth claiming. But the post-storm canvassing economy runs on urgency, and urgency is how people end up signing things on their doorstep that they would not sign at their kitchen table an hour later.
A residential contractor may not advertise or promise to pay, rebate, or absorb any part of your insurance deductible, or offer anything of value to persuade you into an insurance-funded contract. Penalties reach $10,000 per violation, it is punishable as a misdemeanor, and it can cost a contractor its license.
"We'll cover your deductible" is not a deal. It is a contractor telling you they are willing to break the law, and inviting you into a misrepresentation to your own insurer.
What hail does to a metal roof
Metal behaves differently from asphalt under impact, and understanding that keeps you from both over-claiming and under-claiming.
On asphalt, hail bruises the mat beneath the granules. The shingle may look largely intact while its remaining service life has been cut substantially. That is functional damage and it is claimable.
On steel, hail typically dents. The panel keeps shedding water and keeps performing. Insurers generally regard that as cosmetic, and a growing number of policies carry an explicit cosmetic damage exclusion for metal roofing. Functional damage on metal means a puncture, a fractured coating that opens a path to corrosion, a compromised seam or fastener seal, or a displaced panel.
Stone-coated steel sits between the two — the granular surface hides minor dimpling well, which is a genuine advantage on this storm track.
Wind, which is often the bigger problem
Straight-line wind does more roof damage around here than hail does, and it is less often claimed because it is less visible from the ground. On metal, look for lifted edges at the rake and eave, loosened or backed-out fasteners along the windward edge, displaced ridge cap and trim, and seam separation where uplift worked at the panel.
Open exposure matters. A roof on open ground west of town — the Clearwater side of the I-94 corridor — takes uplift at the edges that a sheltered Monticello cul-de-sac simply does not see.
How to handle a claim properly
- Make it safe and stop the damage. Tarp an active leak, get containers under water, move what is at risk. Insurers expect you to mitigate.
- Photograph everything, dated, before anything is touched. Interior and exterior.
- Get an independent inspection. Have somebody who is not selling you a roof that afternoon tell you what is actually damaged.
- Read your policy. Deductible amount, whether it is a flat sum or a percentage of dwelling value, ACV versus replacement cost, and whether a cosmetic damage exclusion applies.
- Decide whether to file. If the repair is near your deductible, filing may cost you more than it returns.
- Be present at the adjuster's inspection if you can, with your contractor there. It is far easier to point at the damage together than to dispute it in writing afterwards.
What we do
We inspect and document: dated photographs, a written description of what is damaged, what is not, and whether in our view it is functional or cosmetic. If your roof is fine, the report says your roof is fine.
We will meet your adjuster on site. We will not tell you what your claim is worth — that is between you and your insurer — and we will not pay, rebate or absorb any part of your deductible, because doing so is illegal in this state.
If the damage is repairable, we repair it. If the roof is genuinely finished, we will tell you that too.